atlastrader: delta-neutral funding rate harvesting (paper trading)
atlastrader is a delta-neutral trading system harvesting the funding rate of Binance USDⓈ-M perpetual futures: a long spot position and an equal-notional short perpetual position. Price exposure is cancelled out — what remains are the funding payments collected every 8 hours, minus fees.
The project is deliberately in a research and paper trading phase: no real orders are sent, the dashboard simulates positions from real market data, and the repository documents the measurements, pitfalls and limits of the strategy in detail.
How it works
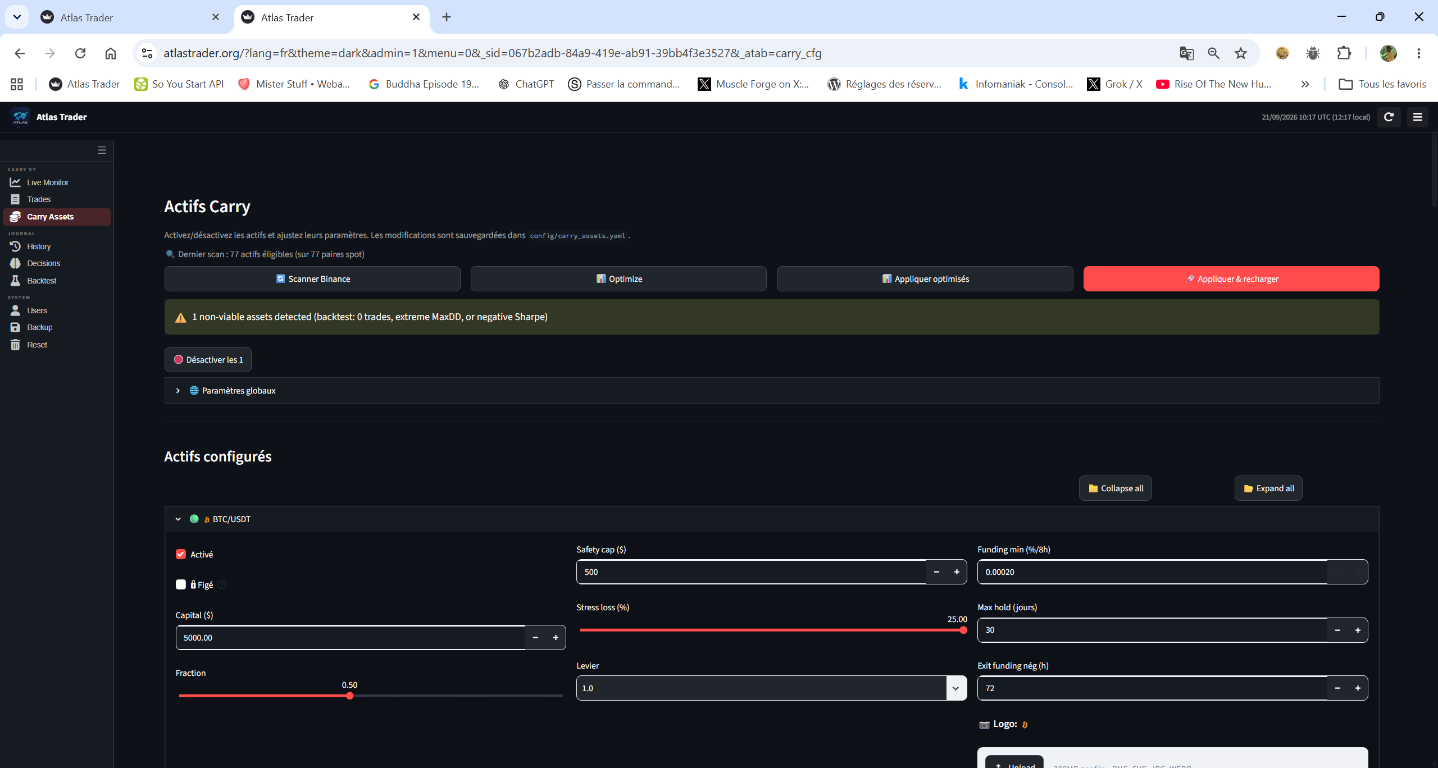
- 8-hour cycle: entry conditions (instant funding between 0.02% and 0.30% per 8h, positive 7-day average, basis > −0.30%, net expected return above the 5%/yr hurdle…)
- Asset selection: Spot∩Perp scanner (volume, open interest) over the eligible universe
- Risk-budget sizing: score = (net return − hurdle) / stress loss, per-asset caps
- Economic exit zones (review, derisk, forced close) + basis stop and negative-funding timer
- 60 s risk monitor: 4-tier kill-switch (operational, market, portfolio drawdown, correlated losses)
- Backtests driven by the same configuration as the live system (1 year, 3-year walk-forward)
Public dashboard
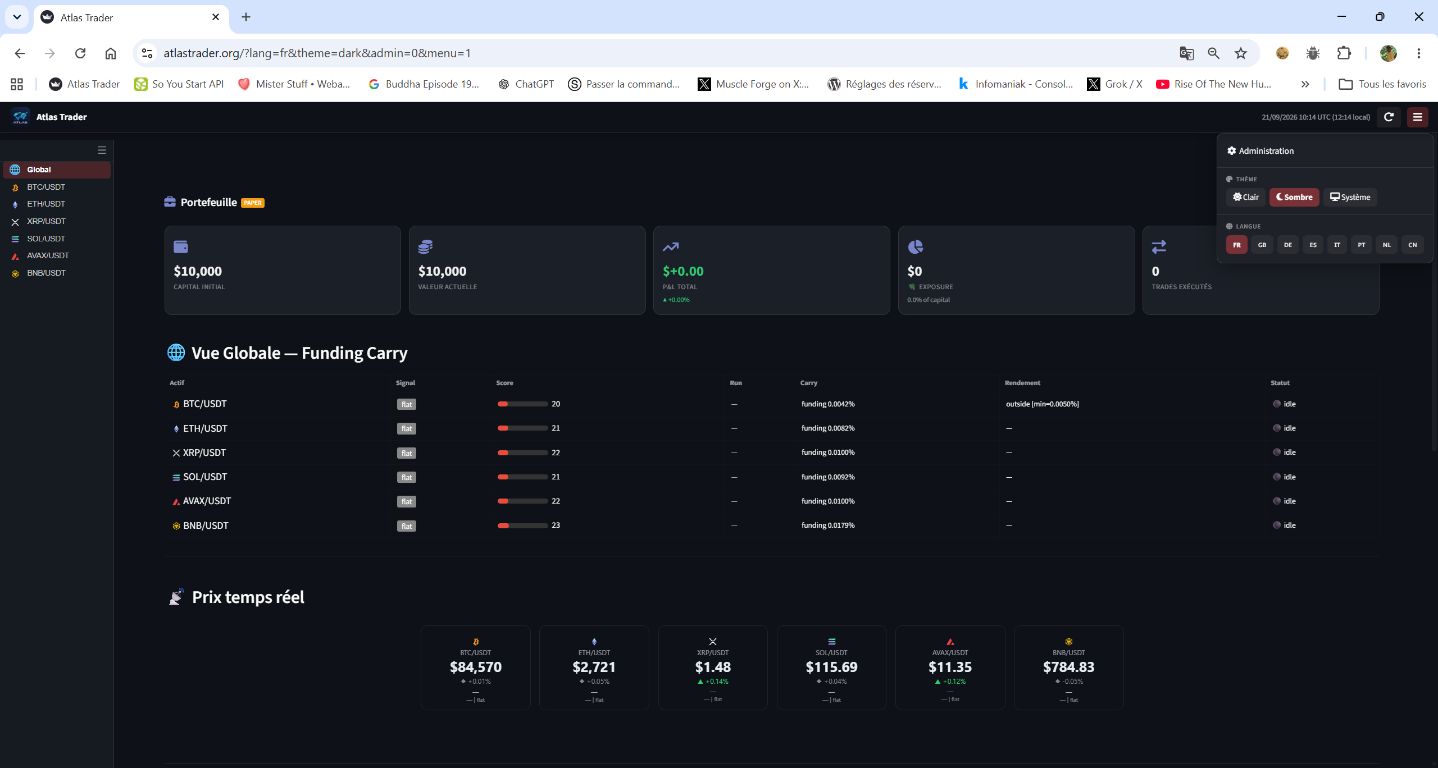
The dashboard is online — paper portfolio, funding carry global view, live prices and decision log:
Source code
Published on GitHub (MIT license, Python): FastAPI API, Streamlit dashboard, SQLite, Docker/Traefik, unit tests and backtests included:
→ github.com/eletec/atlas-trader